 How-to
Volatility Stop Losses: How to Set Them with ATR
Last Updated: November 8, 2026
Quick Summary
A volatility stop loss sets the stop distance using Average True Range (ATR) instead of a fixed percentage, so the stop scales with how much the market is actually moving. Calculate it as entry price minus (ATR × multiplier) for longs, or entry price plus (ATR × multiplier) for shorts, with multipliers commonly starting between 1.5 and 3.
- True range uses the current high minus low, plus distances from the previous close to capture gap risk.
- Most platforms default ATR to 14 periods; test 10, 14, and 20 against your own strategy.
- Convert points to dollars using the contract multiplier, or your risk budget will be wrong.
- Position size equals account equity times risk per trade percent, divided by stop distance in dollars.
- Move stops only in the direction of the trade and recalculate on bar close, not intrabar.
Table of Contents
- What a Volatility Stop Loss Is and Why Fixed Percentages Fail
- How to Build an ATR-Based Stop Loss Step by Step
- Stop-Loss Strategies for Volatile Markets: Anchors, Trailing, and Long vs Short
- Position Sizing Based on Stop Loss Distance
- The Volatility Stop Indicator in TradingView: Setup and Limits
- Gap Risk, Slippage, and Backtesting Your Stop Rules
- Common Failure Modes and the Decision Rules That Fix Them
- Test Your Stop Rules Inside a Duncan Funded Evaluation
- Frequently Asked Questions
What a Volatility Stop Loss Is and Why Fixed Percentages Fail
A volatility stop loss is a stop placed at a distance from your entry that adjusts to how much the market is actually moving, rather than to a fixed percentage of your account.
A fixed stop punishes you in two directions. Set it tight and normal market noise takes you out before the trade develops. Set it wide and one loss does more damage than your plan allows.
Volatility-based stops solve that by scaling the stop to the instrument's recent range. The most common tool for measuring that range is Average True Range, or ATR.
The logic is straightforward: if normal movement is small, your stop can sit closer. If normal movement is large, your stop needs room.
How to Build an ATR-Based Stop Loss Step by Step
Building an ATR-based stop loss takes two measurements and one multiplication: measure how far price normally travels, then decide how many multiples of that distance your stop should sit from entry.
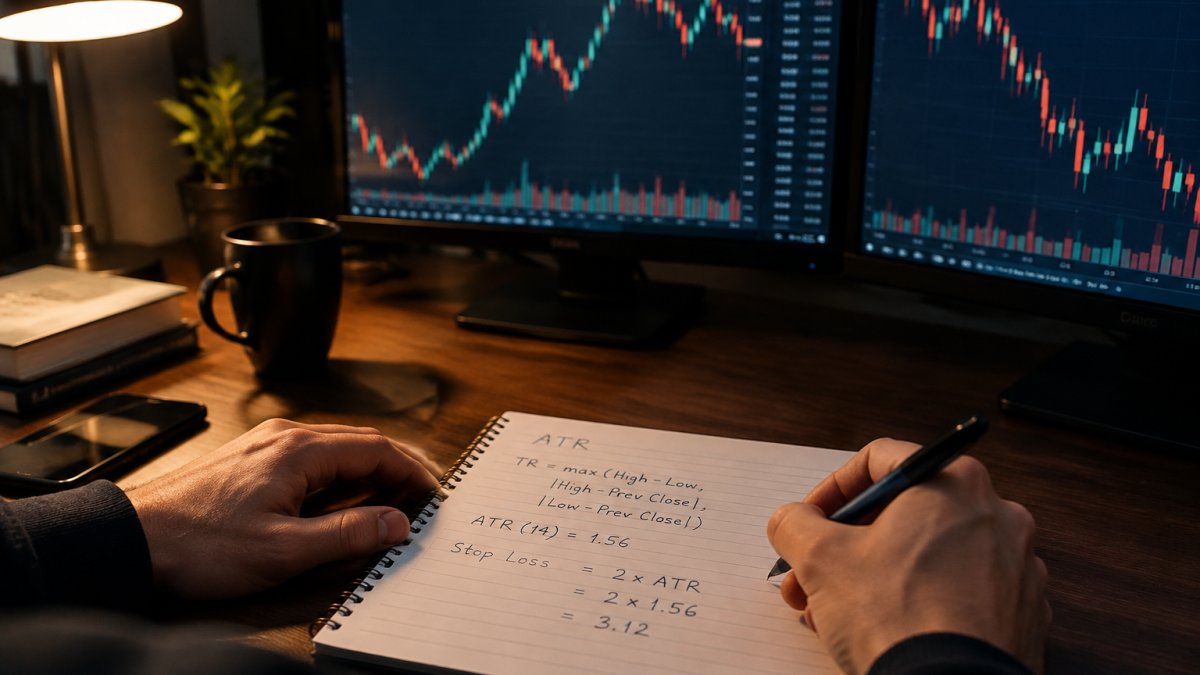
Step 1: Measure True Range and Average It
True range is the largest of three distances on any given bar:
- The current high minus the current low
- The current high minus the previous close
- The current low minus the previous close
Including the previous close is what makes true range different from a simple daily range. It captures gap risk, where price opens beyond yesterday's range.
Average those true range values over your lookback period and you have ATR. Most platforms default to 14 periods. A shorter lookback reacts faster to sudden volatility; a longer one smooths out spikes.
Choosing the lookback and timeframe is a decision, not a default. Match the ATR period and chart timeframe to your holding period. A swing trade held for days to weeks is usually measured on daily bars with a 14-period ATR.
Step 2: Pick an ATR Multiplier and Calculate the Stop Price
The ATR multiplier sets how much breathing room you give the trade. Common starting points sit between 1.5 and 3.
For a long position: stop price = entry price − (ATR × multiplier) For a short position: stop price = entry price + (ATR × multiplier)
A worked example. Suppose ATR on your timeframe reads 2.00 points and you choose a 2.0 multiplier. Your stop distance is 4.00 points.
Now convert points to dollars, because that is what your risk budget actually measures.
The multiplier is a judgment call, not a rule. Higher multipliers survive more market noise but cost more per loss. Lower multipliers cut risk per trade but invite whipsaw.
Stop-Loss Strategies for Volatile Markets: Anchors, Trailing, and Long vs Short
Stop-loss strategies for volatile markets combine two things: a volatility-based distance and a price anchor. The anchor is the support level or resistance level that gives the stop a reason to sit where it does.
Start with the ATR calculation, then check it against structure. If your ATR stop lands just below a clear support level on a long trade, that is a good sign. If it lands above support, the market can sweep your stop and still hold the level, so widen it to sit beyond the anchor. The same logic mirrors on a short: an ATR stop just above resistance is well placed; one below resistance can be swept while the level holds.
Trailing Stops With ATR
Trailing stops follow the same math as price moves in your favor. On a long position, raise the stop to the highest close minus (ATR × multiplier). On a short, lower it to the lowest close plus the same figure. The stop only moves in your direction, never back.
A worked trailing example. Suppose you are long at 100.00 with ATR of 2.00 and a 2.0 multiplier, so your initial stop is 96.00. Price closes at 104.00. The new trailing stop is 104.00 − 4.00 = 100.00, which locks in breakeven. Price then closes at 108.00. The new stop is 108.00 − 4.00 = 104.00, locking in a 4.00-point gain.
Rules for Moving or Not Moving a Stop
- Move the stop only in the direction of the trade. Never widen it to avoid a loss.
- Recalculate the trailing stop on bar close, not intrabar, so normal noise does not trigger a premature exit.
- If volatility expands sharply, decide in advance whether to widen the stop (accepting more risk) or reduce position size (keeping risk constant). Widening without resizing breaks your risk budget.
- Do not move a stop to breakeven purely because the trade is slightly profitable; move it when the ATR trail or the structure anchor justifies it.
Adapting to Changing Volatility
Volatility regimes shift. A market that ranged quietly for weeks can expand its ATR by 50% or more in a few sessions around news or a trend break.
Long and short formulas mirror each other, and that matters when you code them into a platform. A single sign error turns a protective stop into an immediate stop-out.
Watch out: trailing a stop using an ATR that spikes on a single news bar can pull the stop backward or trigger an exit at a worse price than the prior bar's trail would have allowed; smooth the ATR or lock the trail value for the trade if testing shows that pattern.
Position Sizing Based on Stop Loss Distance
Position sizing based on stop loss distance is the step most traders skip, and it is where the stop actually protects your capital.
The formula: position size = (account equity × risk per trade %) ÷ stop distance in dollars per unit.
Say your account equity is $100,000 and your risk per trade is 1%, or $1,000. If your ATR stop distance is 4.00 points on a contract worth $50 per point, one contract risks $200.
Run the same math with a fixed stop and you get a different answer every time volatility shifts. For the full walkthrough of how stop distance, exposure, and risk connect, see our guide on how to calculate position size when trading a funded account.
The Volatility Stop Indicator in TradingView: Setup and Limits
The Volatility Stop indicator in TradingView plots a trailing stop line based on ATR and a multiplier, flipping sides when price closes beyond it.
It is a useful visual check, not an order. The indicator draws a line; it does not place or manage a stop in your broker or platform. You still have to enter the stop yourself.
Two limits matter. First, the indicator recalculates on the bar close by default, so it can lag intrabar moves. Second, it uses whatever timeframe you load it on, and a daily ATR stop behaves nothing like a five-minute one.
We would use it to sanity-check a manual calculation, not to replace one. If the plotted line and your own ATR math disagree, you have a timeframe or input mismatch to fix before you trade.
Gap Risk, Slippage, and Backtesting Your Stop Rules
Gap risk and slippage are where stop rules meet reality. A stop is an instruction to exit at market once a price is touched, not a promise of that price. In fast conditions, your fill can land beyond the stop.
That gap between stop price and fill price is slippage, and it is larger in thin liquidity and around news. Investor.gov's guide to order types explains how market and stop orders behave when price moves quickly.
Backtesting is how you measure this before it costs you. Our article on backtesting a trading strategy covers a structured method for that review. For the execution side, what slippage in trading means for fills is worth reading before you trust a backtest that assumes perfect entries.
Common Failure Modes and the Decision Rules That Fix Them
Most volatility stop failures come from four repeatable mistakes. Each has a decision rule that fixes it.
| Failure mode | What goes wrong | Decision rule |
|---|---|---|
| Multiplier too tight | Normal noise stops the trade early | Raise the multiplier and retest |
| Timeframe mismatch | Daily ATR used on a 5-minute trade | Match ATR timeframe to trade timeframe |
| Stop moved by hand | Plan abandoned mid-trade | Stops move only in your favor |
| Risk per trade ignored | One loss breaks the daily limit | Size from stop distance, always |
The hand-moved stop is the costliest. Widening a stop because the trade "just needs a bit more room" converts a planned loss into an unplanned one.
Stop placement also interacts with daily loss limits. Our guide on how to manage daily loss limits shows how to keep the two in balance.
Watch out: testing a new multiplier for the first time on a live evaluation account, rather than on a demo, is how traders burn an attempt on an untested rule.
Test Your Stop Rules Inside a Duncan Funded Evaluation
Rules you have not tested are guesses. Duncan Funded runs structured simulated evaluations across Forex, Futures, Crypto, and Equities, so you can put your ATR stop rules through a simulated evaluation environment before capital is on the line.
You get a clear assessment of your risk management and trading performance, and successful evaluations open the door to notionally funded accounts where you can manage six-figure simulated capital.
Before you start, read the broader playbook on how risk management helps you pass a prop trading evaluation. Then bring your stop rules and test them properly.
A stop rule that has never been tested under evaluation conditions is not risk management, it is hope.
Frequently Asked Questions
How many ATRs should a stop loss be?
Most traders use a multiplier between 1.5 and 3 ATR, with 2 ATR a common starting point. The right number depends on your timeframe and strategy. A 1 ATR stop sits inside normal market noise and gets hit often. A 4 ATR stop survives noise but shrinks your position size because your risk per trade is spread over a wider stop distance. Test several multipliers on your own historical trades before committing to one.
Should a stop loss be wider in a volatile market?
Yes. A stop-loss strategy for volatile markets has to account for larger daily ranges, or normal price movement will stop you out before your idea plays out. An ATR-based stop widens automatically as volatility rises and tightens as it falls. The trade-off is position size: a wider stop means fewer contracts or shares for the same risk per trade. Keep your dollar risk constant and let the stop distance adjust.
How do you avoid getting stopped out by normal market noise?
Place the stop beyond the range price typically travels in a day, not at an arbitrary round number. Multiply ATR by a factor above 1, then check that the stop sits past nearby support or resistance. Avoid placing stops exactly at obvious levels where clusters of orders sit. Backtesting shows how often your chosen multiplier would have been hit by noise alone before the trade reached its profit target.
How should position size change when using a wider stop loss?
Position sizing based on stop loss distance keeps your risk per trade fixed. Divide the dollar amount you are willing to lose by the distance between entry price and stop price. If your stop widens from $1 to $2 per share, your share count halves for the same risk. On a funded evaluation, this discipline matters because a single oversized trade can breach a daily loss limit and end the account.